Gold loan vs personal loan: which really costs less?
Need money this festive season? A gold loan's lower rate isn't always cheaper. ₹1 lakh worked out both ways, the new RBI gold loan rules, and the risks.
Dhanteras falls on 6 November, and for many families it's a time to buy gold, not borrow against it. But the festive season is also when money gets tight: gifts, travel, a wedding, a repair that can't wait. Two common options are a gold loan and a personal loan.
A gold loan's interest rate is usually lower, but that doesn't always make it cheaper. How you repay matters more than the rate. Here's ₹1 lakh worked out both ways.
How each loan works
- Gold loan: you pledge your gold jewellery or coins with a bank or NBFC. Because the loan is backed by gold, rates are usually lower. Many gold loans are "bullet" loans: you pay interest every month and repay the full amount at the end, within 12 months.
- Personal loan: no security. Rates are usually higher, and you repay with an EMI that covers interest and some of the loan every month.
₹1 lakh for a year, worked out
With example rates of 10% for a gold loan and 14% for a personal loan, both for 12 months:
| Option | What you pay each month | Interest | Fees (with GST) | Total cost |
|---|---|---|---|---|
| Gold loan, interest only, ₹1 lakh repaid at the end | ₹833 | ₹10,000 | ₹590 | ₹10,590 |
| Personal loan, 12 EMIs | ₹8,979 | ₹7,745 | ₹2,360 | ₹10,105 |
| Gold loan, repaid in 12 monthly payments | ₹8,792 | ₹5,499 | ₹590 | ₹6,089 |
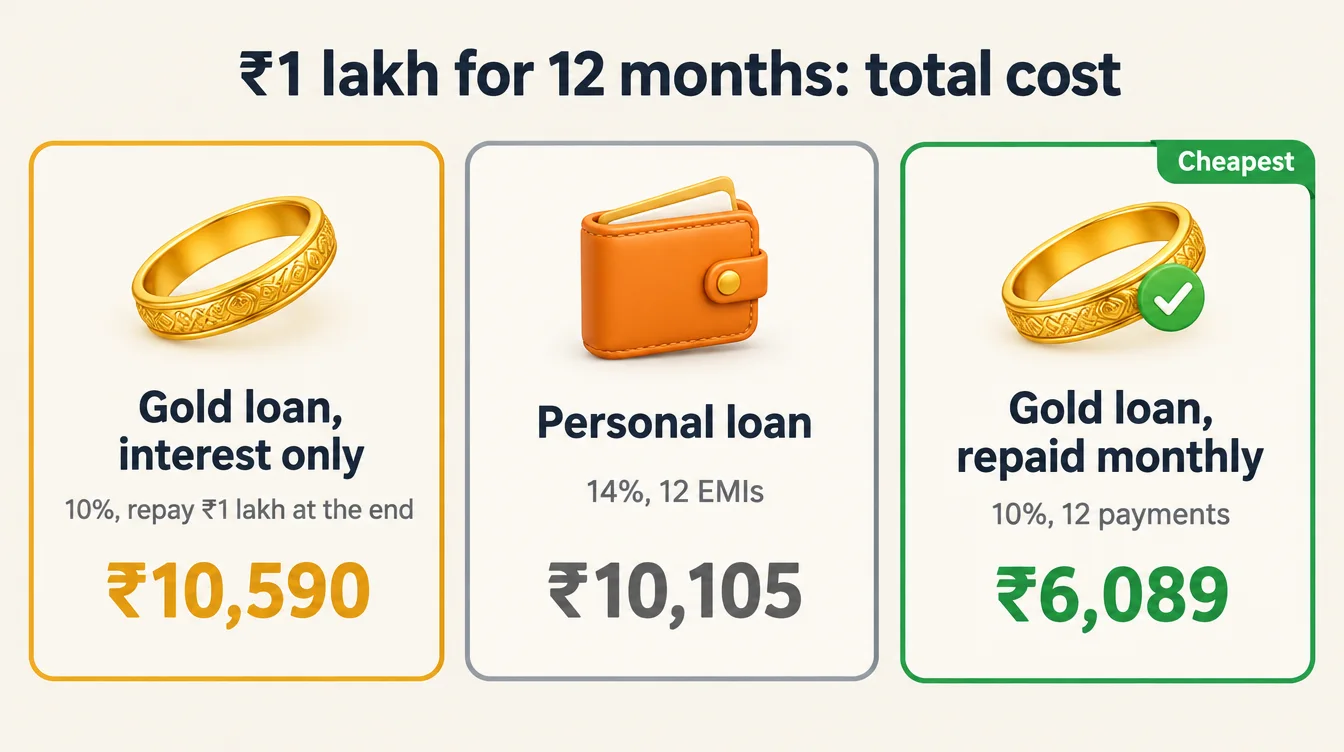
Example rates and fees: we assumed a 0.5% processing fee on the gold loan and 2% on the personal loan, plus 18% GST on fees. Your lender's rates and fees will differ.
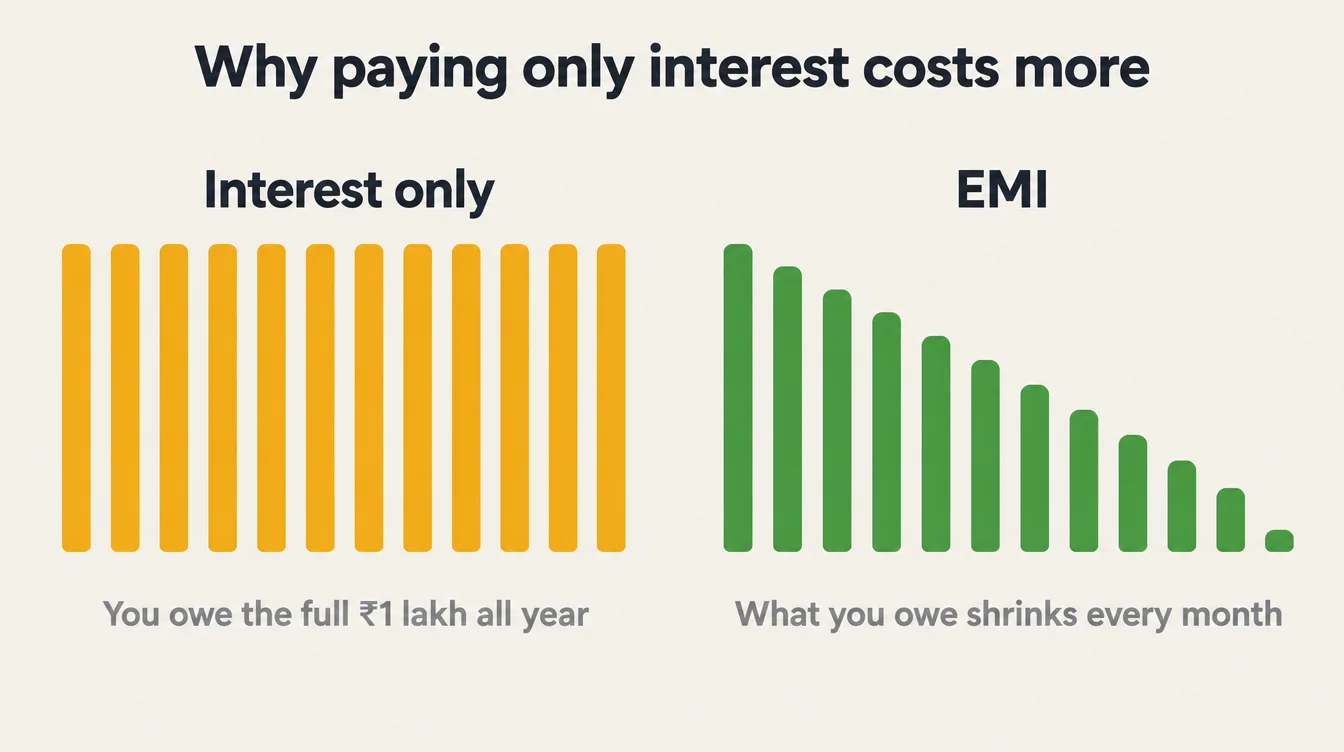
The surprise: paying only interest on the gold loan costs a little more than the personal loan, even though its rate is 4% lower. That's because with a bullet loan you pay interest on the full ₹1 lakh all year. With an EMI, the amount you owe shrinks every month.
The fix: if your gold loan lets you pay back principal each month (many do), it becomes clearly the cheapest, at about ₹6,089.
Need the money for just a few months?
Gold loans shine for short needs. If you need ₹1 lakh for 3 months:
- Gold loan: about ₹2,500 interest + ₹590 fee = about ₹3,090, then you collect your gold.
- Personal loan closed after 3 months: about ₹3,226 interest + ₹2,360 fee = about ₹5,586, plus any foreclosure charge on a fixed-rate loan.
The personal loan's processing fee and fixed EMIs make it expensive for a short need.
The new RBI gold loan rules (from 1 April 2026)
The RBI tightened gold loan rules for all lenders. The key changes:
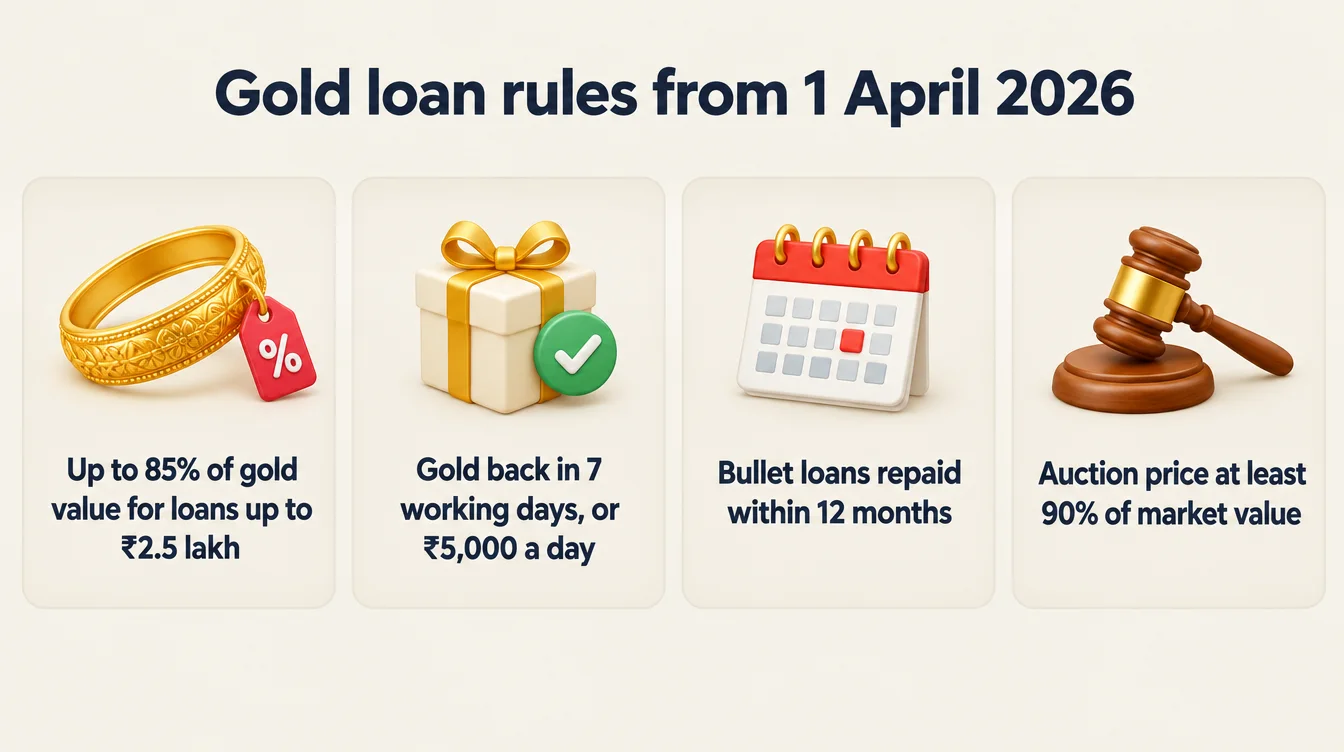
- How much you can borrow: up to 85% of your gold's value for loans up to ₹2.5 lakh, 80% for ₹2.5–5 lakh, and 75% above ₹5 lakh. For a ₹1 lakh loan, you'd need gold worth at least about ₹1.18 lakh.
- How gold is valued: on purity and weight, at the lower of the previous day's price or the 30-day average. Making charges and stones don't count, so jewellery is often valued lower than what you paid for it.
- Bullet loans: interest and principal must be repaid within 12 months.
- Getting your gold back: within 7 working days of closing the loan. If the lender is late, they must pay you ₹5,000 a day.
- If you can't repay: the lender must give notice before an auction, the reserve price must be at least 90% of market value, and any surplus must be returned to you within 7 days.
The risk with a gold loan
The lower rate comes with a real risk: you could lose your gold. For many families, that jewellery is a wedding gift, a mother's bangles or savings built over years. If an emergency means you can't repay, the lender can auction it.
A personal loan doesn't put your gold at risk, but missing EMIs hurts your credit score and brings penal charges, as we explain in what happens if you miss an EMI.
Which one fits?
A gold loan may fit when:
- You need money for a few months and know when you'll repay.
- You can pay back some principal every month, not just interest.
- You have gold you're willing to pledge, and can bear the risk.
A personal loan may fit when:
- You need a longer repayment, more than a year.
- You don't want to risk family gold.
- The EMI fits comfortably in your budget. Check with our EMI affordability guide.
Either way: compare the total cost, not just the rate. Ask for the processing fee, GST, any foreclosure charge and the exact repayment plan in writing.
A Dhanteras thought
Dhanteras is traditionally about buying gold, not borrowing against it. If you're thinking of buying gold or anything else on credit this week, add up the EMI first and see where it leaves your monthly budget. A loan taken for a festival can last long after the lights come down.
The freeeme app keeps every loan, including gold loans and money borrowed from family, in one list, so you can see what each really costs and when your family will be debt-free.
Questions people ask
Is a gold loan cheaper than a personal loan?
Gold loans usually have a lower interest rate, but how you repay matters. If you pay only interest each month and repay the full amount at the end, a gold loan can cost about the same as a personal loan or more. Paying back some principal every month, or borrowing for only a few months, is where a gold loan saves money.
How much loan can I get on my gold?
Under RBI rules from 1 April 2026, lenders can lend up to 85% of your gold's value for loans up to ₹2.5 lakh, 80% for ₹2.5 lakh to ₹5 lakh, and 75% above that. Gold is valued on its purity and weight, not making charges or stones.
What happens if I can't repay a gold loan?
The lender can auction your gold after giving you notice. Under RBI rules, the reserve price must be at least 90% of the gold's market value, and any money left after clearing your dues must be returned to you within seven days.
This is general information to help you understand your options, not financial, legal or tax advice. Rates, rules and charges change; check your lender's latest terms before you decide.