Loan app harassment: what to do, step by step
Threats, calls to your contacts or morphed photos from a loan app? How to tell if the app is illegal, what to do in the first 24 hours, and where to report.
It often starts with a small loan of ₹3,000 or ₹5,000, taken in a hurry from an app. A week later come the calls: abuse, threats, messages to your relatives and colleagues, sometimes even edited photos. If this is happening to you, you are not alone, it is not your fault, and there are clear steps that can stop it. Many of these apps are illegal, and what they are doing is a crime.
Here's how to tell if the app is legal, what to do in the first 24 hours, and exactly where to report.
First: is the app legal?
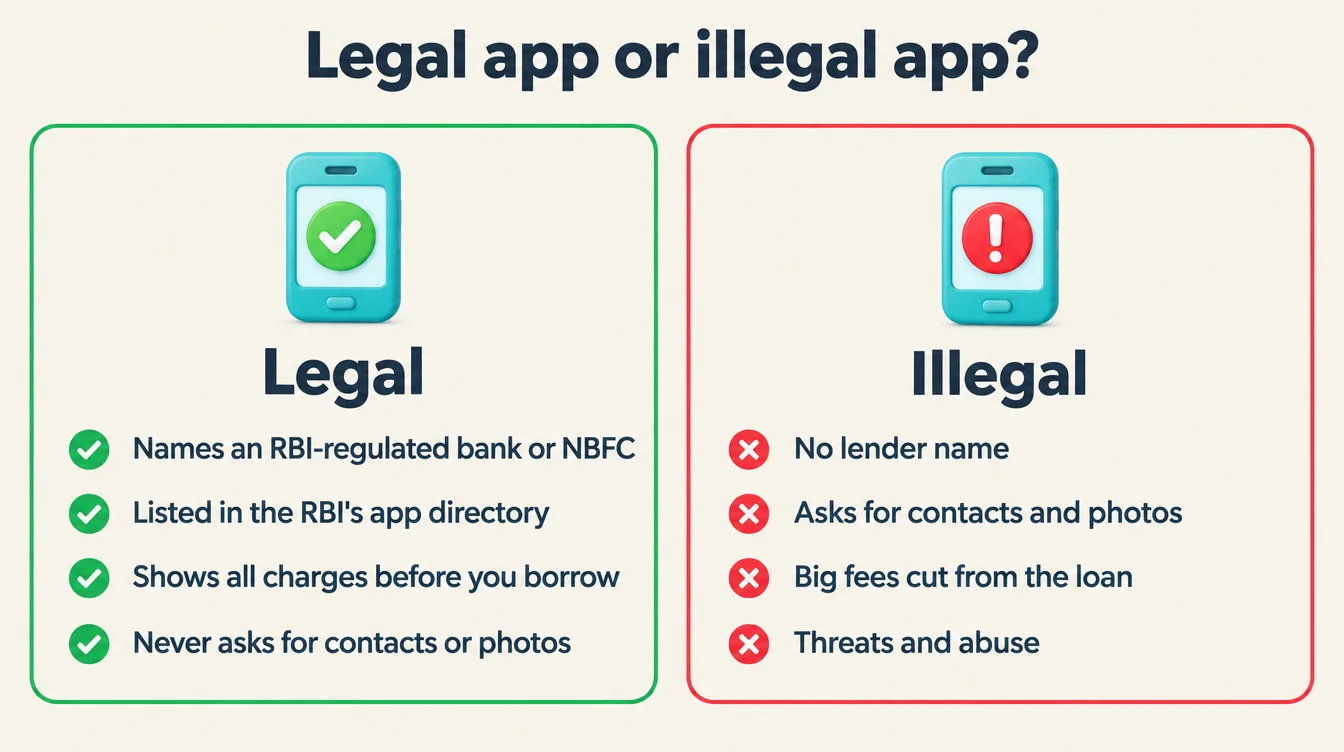
A legal loan app is run by, or for, a bank or NBFC regulated by the RBI. Under the RBI's Digital Lending Directions, 2025, a legal app:
- Names the lender clearly, in the app and the loan papers.
- Shows all charges before you borrow, in a Key Fact Statement: interest, fees and penal charges.
- Pays the loan straight into your bank account, and takes repayments directly to the lender.
- Must not access your photos, files, contact list or call logs.
- Tells you the recovery agent's details by SMS or email before they contact you.
The RBI also publishes a directory of digital lending apps used by regulated lenders on its website, since July 2025. If your app isn't linked to a regulated lender, treat it as illegal.
What these loans really cost
Illegal apps often deduct a big "fee" upfront and give you very little time to repay. A common pattern:
- You apply for ₹5,000. The app deducts ₹1,500 as "processing fee".
- You receive ₹3,500.
- You must repay ₹5,000 in 7 days.
That's ₹1,500 for using ₹3,500 for one week: 43% in seven days, or more than 2,000% a year. For comparison, a personal loan at 13% a year would cost about ₹9 on ₹3,500 for the same week.
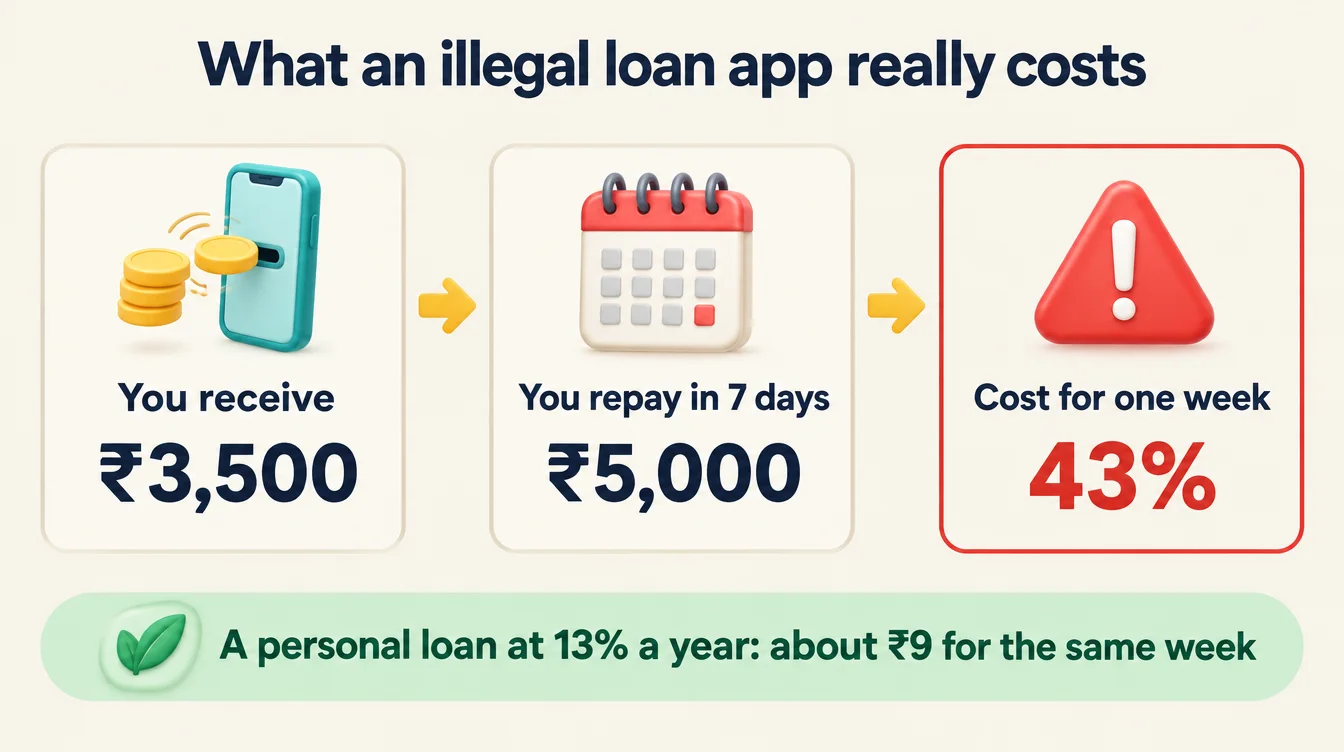
Example figures; actual apps vary. This is why people end up taking a second app's loan to repay the first, and then a third.
What to do in the first 24 hours
1. Don't panic, and don't borrow from another app to pay
A new loan to pay off the old one only adds a second set of threats. Stop and follow the steps below.
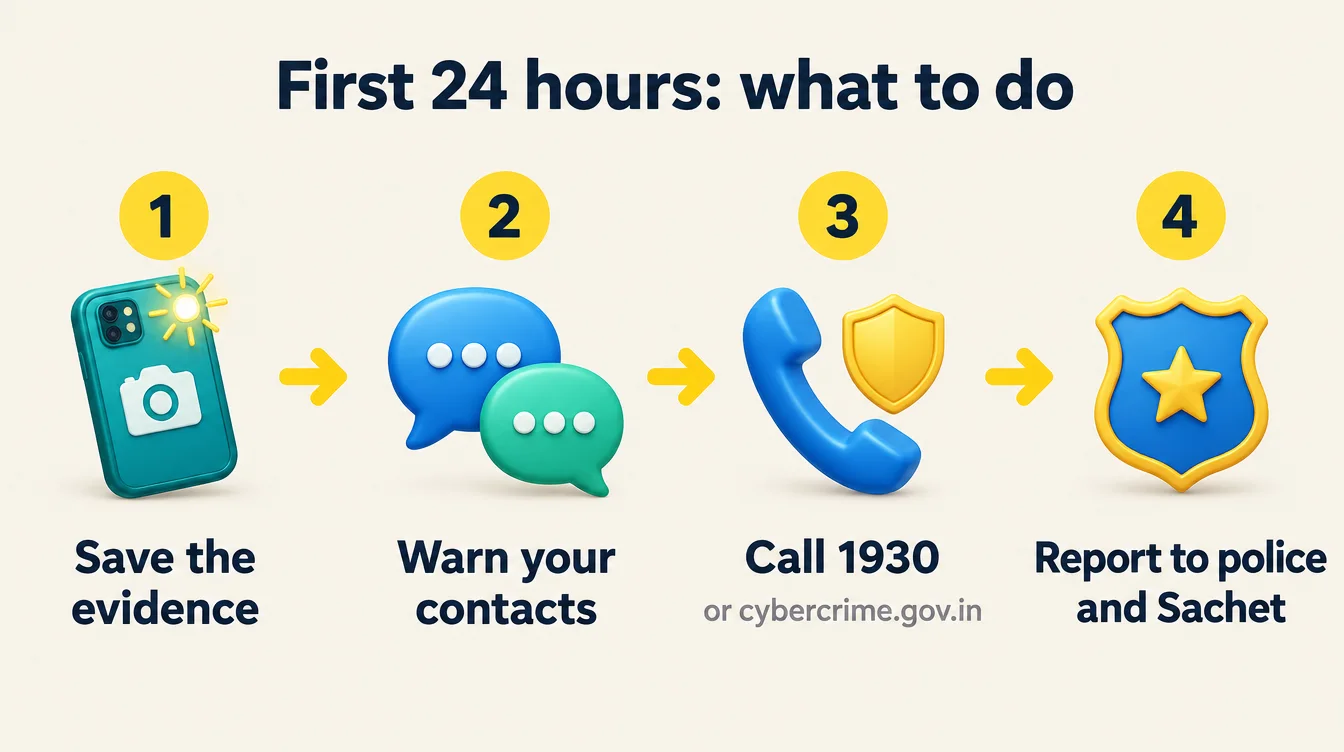
2. Save every piece of evidence
Before you delete anything, take screenshots of the app, messages, WhatsApp chats and call logs. Save the phone numbers that call or message you, any payment proof (UPI screenshots, bank statements) and call recordings if you have them. Note dates and times.
3. Warn your contacts
If the app may have copied your contacts, send a short message to family, friends and colleagues:
"I'm being harassed by an illegal loan app. If you get messages or photos about me, they are fake. Please don't reply or pay anything. I've reported it to the police."
This takes away the app's biggest weapon: shame.
4. Report it
- Cybercrime: call the national helpline 1930, or report at cybercrime.gov.in. Threats, extortion and morphed photos are crimes.
- Police: file a complaint at your nearest police station or cyber cell with your evidence. In an emergency, call 112.
- RBI Sachet: report the unauthorised app at sachet.rbi.org.in.
- The app store: use "Flag as inappropriate" or "Report" on the app's store page.
- If the app belongs to an RBI-regulated bank or NBFC: complain to the lender in writing, and if it isn't fixed within 30 days, at cms.rbi.org.in.
5. Lock down your phone
After saving evidence, remove the app's permissions (contacts, photos, storage) in your phone settings and uninstall it. Change passwords if you shared any, and don't share OTPs with anyone.
6. Be careful about paying more
Paying extra "fees" or amounts demanded under threat rarely stops the harassment, and often leads to bigger demands. Talk to the police cyber cell before you pay anything more. If you did borrow from a legal lender, repay only through official channels and keep proof.
If the lender is legal but the recovery is harsh
Even regulated lenders and their agents must follow rules: no calls before 8 am or after 7 pm, no threats, no shaming your family or colleagues. We explain your rights, and the new rules from January 2027, in loan recovery agents: your rights. If you've missed EMIs on a legal loan, what happens if you miss an EMI explains the real consequences and your options.
You're not alone
Loan app harassment is designed to make you feel trapped and ashamed. You're not, and help is available. If it's affecting your sleep, health or safety, please call Tele-MANAS on 14416, the government's free mental health helpline, or talk to someone you trust today.
Before you borrow from any app again
- Check the lender's name, and that it's an RBI-regulated bank or NBFC.
- Read the Key Fact Statement: the full cost, all fees and the repayment date.
- Never give an app access to your contacts or photos.
- If you need money urgently, ask your bank, employer or family first.
The freeeme app helps you see every loan and due date in one place, so you can plan your way out without reaching for one more app.
Questions people ask
Can a loan app access my contacts and photos?
Under the RBI's Digital Lending Directions 2025, apps of RBI-regulated lenders must not access your phone's files, photos, contact list or call logs. An app that demands these permissions is a warning sign.
How do I check if a loan app is legal?
A legal loan app works for an RBI-regulated bank or NBFC and names it clearly. The RBI publishes a directory of digital lending apps used by regulated lenders on its website, so you can check the app's name there.
Where do I complain about loan app harassment?
Call the national cybercrime helpline 1930 or report at cybercrime.gov.in, and file a police complaint for threats or morphed photos. Report the app on the RBI's Sachet portal. If the app belongs to an RBI-regulated lender, also complain to the lender and then at cms.rbi.org.in.
This is general information to help you understand your options, not financial, legal or tax advice. Rates, rules and charges change; check your lender's latest terms before you decide.